Nursery Financing
Explore funding for a childcare nursery’s equipment, improvements and working capital, with repayments planned around fees and operating costs.
Nursery Business Finance Made Simple
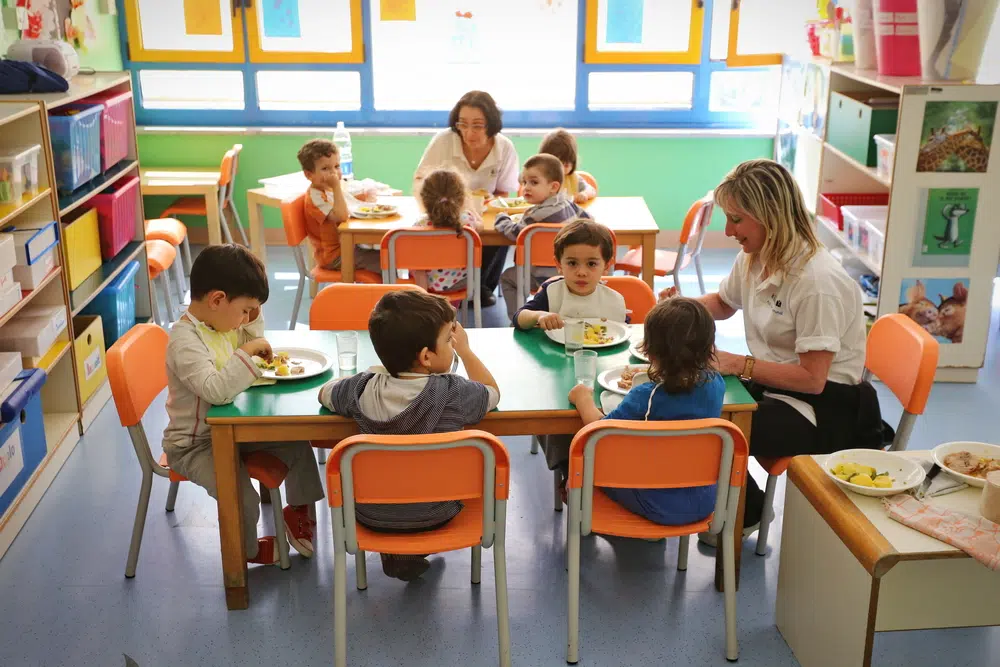
Nursery finance on this page is for childcare businesses, rather than plant nurseries. A childcare provider may need to invest in rooms, equipment or recruitment before additional places generate collected income.
Occupancy, staffing and fee collection need to be considered together. A new room does not produce income simply because it is available: the nursery also needs appropriate staffing and demand. Budget from the first investment through the point when fees are received.
PDQ Funding helps UK businesses explore business loans and merchant cash advances. The available route depends on the business, its payment channels and the provider’s assessment.
For additional premises or capacity, use our guide to business expansion finance. For a defined gap in operating receipts, read about working capital loans.
What could the funding cover?
- Room improvements, furniture and equipment linked to a defined plan.
- Scheduling, billing and nursery administration systems.
- Recruitment and training for a costed expansion.
- A forecast gap between operating payments and fee receipts.
Include implementation time, temporary disruption and the cost of staffing new capacity. Show parent payments and other funding receipts separately. Prepaid fees may need to cover care still to be delivered, so they should not automatically be treated as spare cash for a refit.
Compare the funding structure
Nursery business loans
A business loan may support a defined nursery project where scheduled repayments fit the fee forecast. Equipment finance can be compared for suitable identified assets. Buying a nursery or property involves a separate assessment from ordinary working capital.
A loan provides an agreed sum repaid over a set term, with interest and fees. Ask for the payment schedule and full cost before deciding whether it fits the business.
Funding linked to qualifying card sales
A conventional cash advance requires qualifying card receipts. Parent bank transfers, direct debits and other funding payments are not automatically card sales. Where most fees arrive outside card channels, explain this before pursuing an advance.
A merchant cash advance provides upfront funds, collected through an agreed percentage of qualifying card receipts. Collections can vary with those receipts. Check any minimum payment, reconciliation or other contractual requirements.
Model occupancy alongside staffing costs
Prepare a forecast after payroll, premises, food, supplies and existing finance. Allow for a slower increase in occupancy and uneven receipts through the year. Any planned staffing and capacity changes should be checked against applicable operating requirements.
Compare net funds received, fees and total repayable across quotations. For an advance, the collection percentage is different from the funding fee: a smaller percentage taken from sales does not necessarily mean cheaper funding.
Review security, personal guarantees and early settlement terms. Unsecured funding can still involve a personal guarantee, creating personal liability if the business cannot pay. Consider independent advice before accepting an agreement.
Eligibility and information to prepare
Provide accounts, bank statements, current commitments and an income breakdown. Add an occupancy forecast, project quotations and a timetable. Explain the gap between spending on new capacity and collecting the fees it is expected to produce.
Providers may assess trading history, financial records, credit information, existing commitments and affordability. Requirements vary; an enquiry does not guarantee an offer, amount or completion date. Tell us about other applications or finance already in place so the overall commitment can be considered.
Nursery finance questions
Is this funding for a plant nursery?
No. This page covers childcare nurseries. Garden retailers should use our garden centre finance page.
Can finance help open an additional room?
A defined project may be considered. Include equipment, recruitment, operating requirements and the expected timing of occupied places and collected fees.
Do parent direct debits qualify as card sales?
Not automatically. Direct debits and bank transfers are different from qualifying card transactions used for a conventional advance.
Discuss your funding requirements
Tell us what you need to fund, the amount required and how the business receives income. Complete the online enquiry form or call 01246 233108 to discuss the next steps.
PDQ Funding is a broker, not a lender. We do not charge for using our brokerage service and receive lender commission following a successful introduction. There is no obligation to accept an offer.
For related information, see garden centre finance.
Your funding enquiry
Share your business details and funding needs.